How we’re paid, in full.
People usually ask us this first, so here’s the detail behind the line at the top.
- From the lender
- CommissionUpfront when your loan settles, then a smaller amount each month while the loan runs. Your repayments go to the lender, not to us.
- From you
- Nothing, for a standard home loan. The lender’s commission is how we’re paid.
- When a fee can apply
- If the lender won’t pay commission on your loan, or it isn’t a standard home loan. The fee is in a written quote before any work starts, and you only pay it if you sign.
What you still pay, and to whom
- To the lender
- Interest, and the lender’s own fees.
- To others
- Stamp duty, conveyancing, inspections and insurance when you buy.
- Mortgage insurance
- If your loan needs lenders mortgage insurance, it protects the lender, not you.
Before you apply, you’ll see in writing what the lender would pay us for your loan.
What brings you in?
Home loans are all we do. Tap yours to book a first chat about it.
Who you’ll deal with.
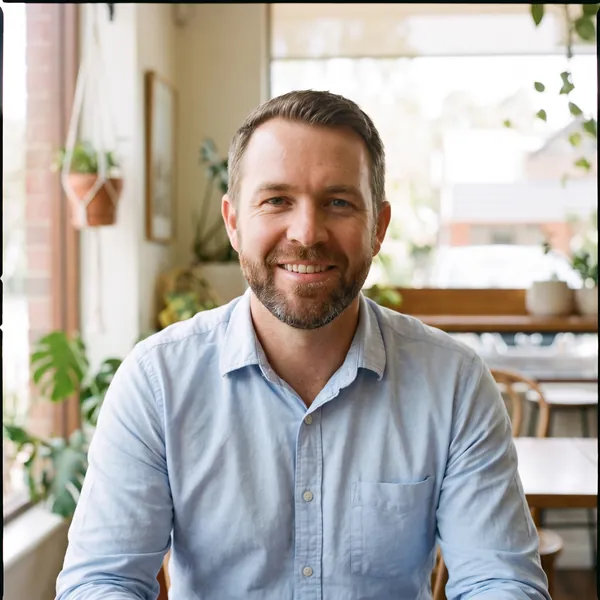
Ben Carter
Mortgage Broker, principal Diploma of Finance and Mortgage Broking ManagementBen set up Copperline for people who want their loan explained properly. He’s the one at the table with you, from the first chat until he rings to say you’ve settled.
Ben’s credit details
Ben is authorised credit representative 000000 (example) of Sample Credit Licensee Pty Ltd, Australian Credit Licence 000000 (example).
You can check a credit representative’s authorisation on ASIC’s registers.The duty Ben works under
By law, a mortgage broker has to act in your best interests. If what suits us and what suits you ever pull in different directions, you come first.
Freya Nolan
Loan ProcessorFreya keeps your file moving: she books your meetings, checks your documents and keeps you posted while the lender does its part. She doesn’t give credit advice. Loan recommendations come from Ben.
The lenders we compare, and the ones we can’t.
We’re accredited with a panel of lenders through our licensee: a mix of banks and non-bank lenders. It’s a wide panel, but it isn’t every lender in Australia. Ask about one that isn’t on it, and we’ll tell you.
- You first. Your deposit, income, how you’re paid, and the features you want, like an offset account or a fixed period.
- Then the panel. We check which lenders on it take on a situation like yours, and which of their loans fit.
- A shortlist, in writing. The loans, what they cost, and why we’d pick one.
- You choose. What a lender pays us doesn’t decide it: the law says your interests come first.
Rates depend on the lender and on you, so you’ll see real ones on your shortlist, in writing, before you choose.
From a first chat to settlement.
We don’t promise dates. Timing depends on the lender and on you.
A first chat
You: tell Ben what you’re buying, and roughly what you earn, owe and have saved.
Your documents
You: upload them through your secure link. Freya checks nothing’s missing.
Your shortlist
You: choose. We show you the loans that fit, their costs, and what each lender pays us.
The application
You: sign it. We lodge it and help with the lender’s questions.
Conditional approval
You: talk to us before signing a contract. It’s a yes with conditions, not the final yes.
Formal approval
You: sign the loan documents, once we’ve been through them with you.
Settlement
You: take Ben’s call. The lender pays out the loan, working with your conveyancer.
After settlement, we check in once a year to see if your loan still suits you. The ongoing commission is what pays for that.
Buying your first home.
Your deposit is only part of it: stamp duty, conveyancing and inspections cost money too. Government help for first home buyers comes in different forms.
- A deposit guaranteeHelps eligible buyers get a loan with a smaller deposit.
- Shared equityThe government pays part of the price. You apply through a participating lender, and a broker can help.
- State helpGrants and stamp duty concessions are set by each state, so the WA rules are the ones that count here.
- Family guaranteeIf a parent is thinking of backing your loan, we talk it through with them too.
Who’s eligible and what’s on offer can change, so we check the current rules with you, and whether a participating lender is on our panel. Being eligible doesn’t mean a loan is approved: the lender still assesses it.
You can read up on your own here:
What to bring, and where it goes.
Nothing for the first chat. After it, lenders usually want these. Each asks for slightly different things, so we’ll send you your own list.
- Photo ID: a driver’s licence or passport
- Income: recent payslips, if you’re paid a wage
- Bank statements: savings and everyday accounts
- What you owe: cards, car and personal loans
- Refinancing: a recent home loan statement
If you’re self-employed
Lenders look at your income differently, usually through your tax returns and business financials, and some ask for more. We’ll tell you which lenders on our panel suit how you’re paid.
Where documents go
Through the secure upload link we send after the first chat. Never by email, and never through the enquiry form on this site.
Questions people ask us.
Do I pay you?
For a standard home loan, no: the lender pays us. If a fee would apply, you’d get a written quote with the amount first, and you’d only pay it if you signed. How we’re paid.
How much can I borrow?
It depends on your income, your expenses, what you already owe and your deposit, and each lender works it out its own way. We can give you an estimate at the first chat, but an estimate isn’t an approval. Only the lender approves a loan.
How much deposit do I need?
Enough for the deposit your lender wants, plus buying costs like stamp duty, conveyancing and inspections. If you’re a first home buyer, government help may mean a smaller deposit, depending on whether you’re eligible. We’ll work out your numbers with you.
Is refinancing worth it?
Sometimes. We compare what your current loan costs with a new one, including the costs of switching, and we check the loan term: a lower repayment over a longer term can cost you more overall.
How long does it all take?
It depends on the lender and on your situation, so we won’t promise a date. We’ll tell you where your loan is at each step. If you have a finance date coming up, call us early.
Meet at our office, a cafe, or on video.
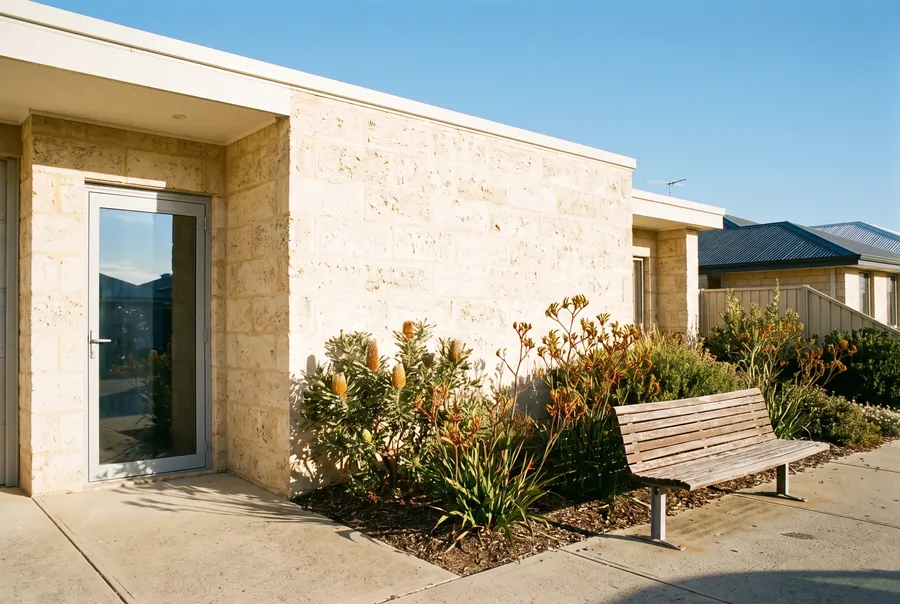
Unit 4, 70 Grand Boulevard
Joondalup WA 6027
- At our officeOn Grand Boulevard. Book ahead so Ben is in.
- At a cafe near youBen comes to you, anywhere in the northern suburbs.
- On videoFrom home or work, whichever is easier. You’ll get a link the day before.
- Mon to Fri
- 9am to 5:30pm
- Saturday
- By appointment
- Sunday
- Closed
Mon to Fri, 9am to 5:30pm